What’s wrong
with U.S. bonds?
Trump’s promises.
The borrowing bill.
Tax cuts, tariffs, war and a $5,000 election promise. The deals are made in Washington. The cost reaches the Treasury, the mortgage offer and the household budget.
Jump to a section
A bond-market question. A military answer.
On the tarmac at Joint Base Andrews, a reporter asked Donald Trump what came next. His Treasury secretary had intervened in the bond market. Yields were climbing again. Would there be another intervention?1
“The ultimate intervention is our military, and if we have to use that, we will.”
Donald Trump · August 21, 2026
Trump had just praised Scott Bessent’s touch with bonds and interest rates. Then came the military answer, and the questions moved on to beef imports. The exchange lasted moments. The borrowing problem has lasted rather longer.1
By October 23, the Treasury’s 10-year yield stood at 5.00%; the 30-year yield was 5.33%. Washington had finished the fiscal year with a $1.99 trillion deficit and a $1.05 trillion net interest bill. These are the numbers behind the administration’s promises of easy money.23
This investigation follows the decisions that put pressure on that bill: a tax law financed with more debt, a tariff shock that rattled Treasury trading, a war feeding energy costs, and an election pledge worth more than a trillion dollars. It also follows the machinery beneath the politics: the traders borrowing heavily to buy government debt, and the Treasury secretary trying to keep the market moving.
The market Trump couldn’t order around.
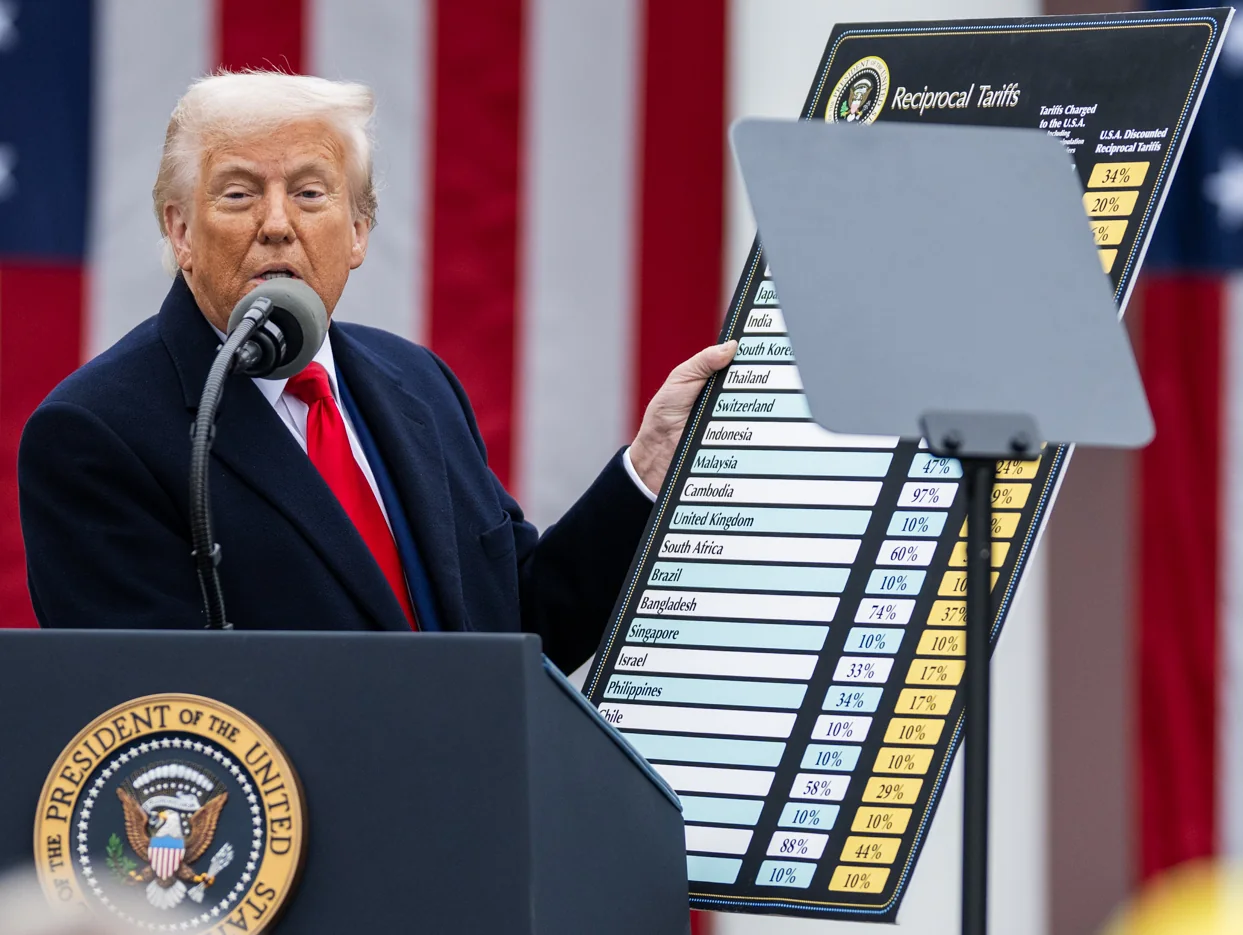
Trump held up his tariff chart in the Rose Garden on April 2, 2025. Country by country, the board advertised the new price of doing business with America. Over the next week, the consequences spread well beyond imports.
Treasuries initially rallied as investors sought safety. Then the market turned. From the evening of April 6 to midnight on April 8, the 10-year yield jumped roughly 0.6 percentage points, according to New York Fed researchers. Trading became more difficult just when investors wanted to move.4
On April 9, Trump paused most of the new country-specific tariffs for 90 days. Yields fell after the announcement. The bond market had forced its way into a political spectacle staged around presidential control.4

The price Washington pays to borrow
View the data
| Date | 10-year Treasury | 30-year Treasury |
|---|---|---|
| Jan 2, 2025 | 4.57% | 4.79% |
| Jan 3, 2025 | 4.60% | 4.82% |
| Jan 6, 2025 | 4.62% | 4.85% |
| Jan 7, 2025 | 4.67% | 4.91% |
| Jan 8, 2025 | 4.67% | 4.91% |
| Jan 9, 2025 | 4.68% | 4.92% |
| Jan 10, 2025 | 4.77% | 4.96% |
| Jan 13, 2025 | 4.79% | 4.97% |
| Jan 14, 2025 | 4.78% | 4.98% |
| Jan 15, 2025 | 4.66% | 4.88% |
| Jan 16, 2025 | 4.61% | 4.84% |
| Jan 17, 2025 | 4.61% | 4.84% |
| Jan 21, 2025 | 4.57% | 4.80% |
| Jan 22, 2025 | 4.60% | 4.82% |
| Jan 23, 2025 | 4.65% | 4.87% |
| Jan 24, 2025 | 4.63% | 4.85% |
| Jan 27, 2025 | 4.53% | 4.76% |
| Jan 28, 2025 | 4.55% | 4.78% |
| Jan 29, 2025 | 4.55% | 4.79% |
| Jan 30, 2025 | 4.52% | 4.76% |
| Jan 31, 2025 | 4.58% | 4.83% |
| Feb 3, 2025 | 4.54% | 4.77% |
| Feb 4, 2025 | 4.52% | 4.75% |
| Feb 5, 2025 | 4.43% | 4.64% |
| Feb 6, 2025 | 4.45% | 4.65% |
| Feb 7, 2025 | 4.49% | 4.69% |
| Feb 10, 2025 | 4.51% | 4.71% |
| Feb 11, 2025 | 4.54% | 4.75% |
| Feb 12, 2025 | 4.62% | 4.83% |
| Feb 13, 2025 | 4.52% | 4.72% |
| Feb 14, 2025 | 4.47% | 4.69% |
| Feb 18, 2025 | 4.55% | 4.77% |
| Feb 19, 2025 | 4.53% | 4.76% |
| Feb 20, 2025 | 4.50% | 4.74% |
| Feb 21, 2025 | 4.42% | 4.67% |
| Feb 24, 2025 | 4.40% | 4.66% |
| Feb 25, 2025 | 4.30% | 4.55% |
| Feb 26, 2025 | 4.25% | 4.51% |
| Feb 27, 2025 | 4.29% | 4.56% |
| Feb 28, 2025 | 4.24% | 4.51% |
| Mar 3, 2025 | 4.16% | 4.45% |
| Mar 4, 2025 | 4.22% | 4.53% |
| Mar 5, 2025 | 4.28% | 4.57% |
| Mar 6, 2025 | 4.29% | 4.58% |
| Mar 7, 2025 | 4.32% | 4.62% |
| Mar 10, 2025 | 4.22% | 4.54% |
| Mar 11, 2025 | 4.28% | 4.59% |
| Mar 12, 2025 | 4.32% | 4.63% |
| Mar 13, 2025 | 4.27% | 4.59% |
| Mar 14, 2025 | 4.31% | 4.62% |
| Mar 17, 2025 | 4.31% | 4.60% |
| Mar 18, 2025 | 4.29% | 4.58% |
| Mar 19, 2025 | 4.25% | 4.56% |
| Mar 20, 2025 | 4.24% | 4.55% |
| Mar 21, 2025 | 4.25% | 4.59% |
| Mar 24, 2025 | 4.34% | 4.66% |
| Mar 25, 2025 | 4.31% | 4.65% |
| Mar 26, 2025 | 4.35% | 4.69% |
| Mar 27, 2025 | 4.38% | 4.73% |
| Mar 28, 2025 | 4.27% | 4.64% |
| Mar 31, 2025 | 4.23% | 4.59% |
| Apr 1, 2025 | 4.17% | 4.52% |
| Apr 2, 2025 | 4.20% | 4.54% |
| Apr 3, 2025 | 4.06% | 4.49% |
| Apr 4, 2025 | 4.01% | 4.41% |
| Apr 7, 2025 | 4.15% | 4.58% |
| Apr 8, 2025 | 4.26% | 4.71% |
| Apr 9, 2025 | 4.34% | 4.72% |
| Apr 10, 2025 | 4.40% | 4.86% |
| Apr 11, 2025 | 4.48% | 4.85% |
| Apr 14, 2025 | 4.38% | 4.80% |
| Apr 15, 2025 | 4.35% | 4.79% |
| Apr 16, 2025 | 4.29% | 4.74% |
| Apr 17, 2025 | 4.34% | 4.80% |
| Apr 21, 2025 | 4.42% | 4.91% |
| Apr 22, 2025 | 4.41% | 4.88% |
| Apr 23, 2025 | 4.40% | 4.83% |
| Apr 24, 2025 | 4.32% | 4.77% |
| Apr 25, 2025 | 4.29% | 4.74% |
| Apr 28, 2025 | 4.23% | 4.69% |
| Apr 29, 2025 | 4.19% | 4.64% |
| Apr 30, 2025 | 4.17% | 4.66% |
| May 1, 2025 | 4.25% | 4.74% |
| May 2, 2025 | 4.33% | 4.79% |
| May 5, 2025 | 4.36% | 4.83% |
| May 6, 2025 | 4.30% | 4.81% |
| May 7, 2025 | 4.26% | 4.77% |
| May 8, 2025 | 4.37% | 4.83% |
| May 9, 2025 | 4.37% | 4.83% |
| May 12, 2025 | 4.45% | 4.89% |
| May 13, 2025 | 4.49% | 4.94% |
| May 14, 2025 | 4.53% | 4.97% |
| May 15, 2025 | 4.45% | 4.91% |
| May 16, 2025 | 4.43% | 4.89% |
| May 19, 2025 | 4.46% | 4.92% |
| May 20, 2025 | 4.48% | 4.96% |
| May 21, 2025 | 4.58% | 5.08% |
| May 22, 2025 | 4.54% | 5.05% |
| May 23, 2025 | 4.51% | 5.04% |
| May 27, 2025 | 4.43% | 4.94% |
| May 28, 2025 | 4.47% | 4.97% |
| May 29, 2025 | 4.43% | 4.92% |
| May 30, 2025 | 4.41% | 4.92% |
| Jun 2, 2025 | 4.46% | 4.99% |
| Jun 3, 2025 | 4.46% | 4.98% |
| Jun 4, 2025 | 4.37% | 4.89% |
| Jun 5, 2025 | 4.40% | 4.88% |
| Jun 6, 2025 | 4.51% | 4.97% |
| Jun 9, 2025 | 4.49% | 4.95% |
| Jun 10, 2025 | 4.47% | 4.93% |
| Jun 11, 2025 | 4.41% | 4.91% |
| Jun 12, 2025 | 4.36% | 4.84% |
| Jun 13, 2025 | 4.41% | 4.90% |
| Jun 16, 2025 | 4.46% | 4.96% |
| Jun 17, 2025 | 4.39% | 4.88% |
| Jun 18, 2025 | 4.38% | 4.88% |
| Jun 20, 2025 | 4.38% | 4.89% |
| Jun 23, 2025 | 4.34% | 4.87% |
| Jun 24, 2025 | 4.30% | 4.83% |
| Jun 25, 2025 | 4.29% | 4.83% |
| Jun 26, 2025 | 4.26% | 4.81% |
| Jun 27, 2025 | 4.29% | 4.85% |
| Jun 30, 2025 | 4.24% | 4.78% |
| Jul 1, 2025 | 4.26% | 4.78% |
| Jul 2, 2025 | 4.30% | 4.82% |
| Jul 3, 2025 | 4.35% | 4.86% |
| Jul 7, 2025 | 4.40% | 4.92% |
| Jul 8, 2025 | 4.42% | 4.94% |
| Jul 9, 2025 | 4.34% | 4.87% |
| Jul 10, 2025 | 4.35% | 4.86% |
| Jul 11, 2025 | 4.43% | 4.96% |
| Jul 14, 2025 | 4.43% | 4.97% |
| Jul 15, 2025 | 4.50% | 5.01% |
| Jul 16, 2025 | 4.46% | 5.01% |
| Jul 17, 2025 | 4.47% | 5.01% |
| Jul 18, 2025 | 4.44% | 5.00% |
| Jul 21, 2025 | 4.38% | 4.94% |
| Jul 22, 2025 | 4.35% | 4.90% |
| Jul 23, 2025 | 4.40% | 4.95% |
| Jul 24, 2025 | 4.43% | 4.96% |
| Jul 25, 2025 | 4.40% | 4.92% |
| Jul 28, 2025 | 4.42% | 4.96% |
| Jul 29, 2025 | 4.34% | 4.86% |
| Jul 30, 2025 | 4.38% | 4.89% |
| Jul 31, 2025 | 4.37% | 4.89% |
| Aug 1, 2025 | 4.23% | 4.81% |
| Aug 4, 2025 | 4.22% | 4.80% |
| Aug 5, 2025 | 4.22% | 4.78% |
| Aug 6, 2025 | 4.22% | 4.81% |
| Aug 7, 2025 | 4.23% | 4.81% |
| Aug 8, 2025 | 4.27% | 4.85% |
| Aug 11, 2025 | 4.27% | 4.84% |
| Aug 12, 2025 | 4.29% | 4.88% |
| Aug 13, 2025 | 4.24% | 4.83% |
| Aug 14, 2025 | 4.29% | 4.88% |
| Aug 15, 2025 | 4.33% | 4.92% |
| Aug 18, 2025 | 4.34% | 4.94% |
| Aug 19, 2025 | 4.30% | 4.90% |
| Aug 20, 2025 | 4.29% | 4.89% |
| Aug 21, 2025 | 4.33% | 4.92% |
| Aug 22, 2025 | 4.26% | 4.88% |
| Aug 25, 2025 | 4.28% | 4.89% |
| Aug 26, 2025 | 4.26% | 4.90% |
| Aug 27, 2025 | 4.24% | 4.91% |
| Aug 28, 2025 | 4.22% | 4.88% |
| Aug 29, 2025 | 4.23% | 4.92% |
| Sep 2, 2025 | 4.28% | 4.97% |
| Sep 3, 2025 | 4.22% | 4.90% |
| Sep 4, 2025 | 4.17% | 4.86% |
| Sep 5, 2025 | 4.10% | 4.78% |
| Sep 8, 2025 | 4.05% | 4.69% |
| Sep 9, 2025 | 4.08% | 4.72% |
| Sep 10, 2025 | 4.04% | 4.69% |
| Sep 11, 2025 | 4.01% | 4.65% |
| Sep 12, 2025 | 4.06% | 4.68% |
| Sep 15, 2025 | 4.05% | 4.66% |
| Sep 16, 2025 | 4.04% | 4.65% |
| Sep 17, 2025 | 4.06% | 4.66% |
| Sep 18, 2025 | 4.11% | 4.72% |
| Sep 19, 2025 | 4.14% | 4.75% |
| Sep 22, 2025 | 4.15% | 4.77% |
| Sep 23, 2025 | 4.12% | 4.73% |
| Sep 24, 2025 | 4.16% | 4.76% |
| Sep 25, 2025 | 4.18% | 4.75% |
| Sep 26, 2025 | 4.20% | 4.77% |
| Sep 29, 2025 | 4.15% | 4.71% |
| Sep 30, 2025 | 4.16% | 4.73% |
| Oct 1, 2025 | 4.12% | 4.72% |
| Oct 2, 2025 | 4.10% | 4.69% |
| Oct 3, 2025 | 4.13% | 4.71% |
| Oct 6, 2025 | 4.18% | 4.76% |
| Oct 7, 2025 | 4.14% | 4.73% |
| Oct 8, 2025 | 4.13% | 4.72% |
| Oct 9, 2025 | 4.14% | 4.72% |
| Oct 10, 2025 | 4.05% | 4.63% |
| Oct 14, 2025 | 4.03% | 4.62% |
| Oct 15, 2025 | 4.05% | 4.64% |
| Oct 16, 2025 | 3.99% | 4.58% |
| Oct 17, 2025 | 4.02% | 4.60% |
| Oct 20, 2025 | 4.00% | 4.58% |
| Oct 21, 2025 | 3.98% | 4.55% |
| Oct 22, 2025 | 3.97% | 4.54% |
| Oct 23, 2025 | 4.01% | 4.58% |
| Oct 24, 2025 | 4.02% | 4.59% |
| Oct 27, 2025 | 4.01% | 4.57% |
| Oct 28, 2025 | 3.99% | 4.55% |
| Oct 29, 2025 | 4.08% | 4.61% |
| Oct 30, 2025 | 4.11% | 4.65% |
| Oct 31, 2025 | 4.11% | 4.67% |
| Nov 3, 2025 | 4.13% | 4.69% |
| Nov 4, 2025 | 4.10% | 4.67% |
| Nov 5, 2025 | 4.17% | 4.74% |
| Nov 6, 2025 | 4.11% | 4.69% |
| Nov 7, 2025 | 4.11% | 4.70% |
| Nov 10, 2025 | 4.13% | 4.71% |
| Nov 12, 2025 | 4.08% | 4.67% |
| Nov 13, 2025 | 4.11% | 4.70% |
| Nov 14, 2025 | 4.14% | 4.74% |
| Nov 17, 2025 | 4.13% | 4.73% |
| Nov 18, 2025 | 4.12% | 4.74% |
| Nov 19, 2025 | 4.13% | 4.75% |
| Nov 20, 2025 | 4.10% | 4.73% |
| Nov 21, 2025 | 4.06% | 4.71% |
| Nov 24, 2025 | 4.04% | 4.68% |
| Nov 25, 2025 | 4.01% | 4.67% |
| Nov 26, 2025 | 4.00% | 4.64% |
| Nov 28, 2025 | 4.02% | 4.67% |
| Dec 1, 2025 | 4.09% | 4.74% |
| Dec 2, 2025 | 4.09% | 4.74% |
| Dec 3, 2025 | 4.06% | 4.73% |
| Dec 4, 2025 | 4.11% | 4.76% |
| Dec 5, 2025 | 4.14% | 4.79% |
| Dec 8, 2025 | 4.17% | 4.81% |
| Dec 9, 2025 | 4.18% | 4.80% |
| Dec 10, 2025 | 4.13% | 4.78% |
| Dec 11, 2025 | 4.14% | 4.79% |
| Dec 12, 2025 | 4.19% | 4.85% |
| Dec 15, 2025 | 4.18% | 4.84% |
| Dec 16, 2025 | 4.15% | 4.82% |
| Dec 17, 2025 | 4.16% | 4.83% |
| Dec 18, 2025 | 4.12% | 4.80% |
| Dec 19, 2025 | 4.16% | 4.82% |
| Dec 22, 2025 | 4.17% | 4.84% |
| Dec 23, 2025 | 4.18% | 4.83% |
| Dec 24, 2025 | 4.15% | 4.79% |
| Dec 26, 2025 | 4.14% | 4.81% |
| Dec 29, 2025 | 4.12% | 4.80% |
| Dec 30, 2025 | 4.14% | 4.81% |
| Dec 31, 2025 | 4.18% | 4.84% |
| Jan 2, 2026 | 4.19% | 4.86% |
| Jan 5, 2026 | 4.17% | 4.85% |
| Jan 6, 2026 | 4.18% | 4.86% |
| Jan 7, 2026 | 4.15% | 4.82% |
| Jan 8, 2026 | 4.19% | 4.85% |
| Jan 9, 2026 | 4.18% | 4.82% |
| Jan 12, 2026 | 4.19% | 4.83% |
| Jan 13, 2026 | 4.18% | 4.83% |
| Jan 14, 2026 | 4.15% | 4.79% |
| Jan 15, 2026 | 4.17% | 4.79% |
| Jan 16, 2026 | 4.24% | 4.83% |
| Jan 20, 2026 | 4.30% | 4.91% |
| Jan 21, 2026 | 4.26% | 4.87% |
| Jan 22, 2026 | 4.26% | 4.84% |
| Jan 23, 2026 | 4.24% | 4.82% |
| Jan 26, 2026 | 4.22% | 4.80% |
| Jan 27, 2026 | 4.24% | 4.83% |
| Jan 28, 2026 | 4.26% | 4.85% |
| Jan 29, 2026 | 4.24% | 4.85% |
| Jan 30, 2026 | 4.26% | 4.87% |
| Feb 2, 2026 | 4.29% | 4.90% |
| Feb 3, 2026 | 4.28% | 4.90% |
| Feb 4, 2026 | 4.29% | 4.91% |
| Feb 5, 2026 | 4.21% | 4.85% |
| Feb 6, 2026 | 4.22% | 4.85% |
| Feb 9, 2026 | 4.22% | 4.85% |
| Feb 10, 2026 | 4.16% | 4.78% |
| Feb 11, 2026 | 4.18% | 4.82% |
| Feb 12, 2026 | 4.09% | 4.72% |
| Feb 13, 2026 | 4.04% | 4.69% |
| Feb 17, 2026 | 4.05% | 4.68% |
| Feb 18, 2026 | 4.09% | 4.71% |
| Feb 19, 2026 | 4.08% | 4.70% |
| Feb 20, 2026 | 4.08% | 4.72% |
| Feb 23, 2026 | 4.03% | 4.70% |
| Feb 24, 2026 | 4.04% | 4.70% |
| Feb 25, 2026 | 4.05% | 4.70% |
| Feb 26, 2026 | 4.02% | 4.67% |
| Feb 27, 2026 | 3.97% | 4.64% |
| Mar 2, 2026 | 4.05% | 4.70% |
| Mar 3, 2026 | 4.06% | 4.70% |
| Mar 4, 2026 | 4.09% | 4.72% |
| Mar 5, 2026 | 4.13% | 4.74% |
| Mar 6, 2026 | 4.15% | 4.77% |
| Mar 9, 2026 | 4.12% | 4.72% |
| Mar 10, 2026 | 4.15% | 4.78% |
| Mar 11, 2026 | 4.21% | 4.86% |
| Mar 12, 2026 | 4.27% | 4.88% |
| Mar 13, 2026 | 4.28% | 4.90% |
| Mar 16, 2026 | 4.23% | 4.86% |
| Mar 17, 2026 | 4.20% | 4.85% |
| Mar 18, 2026 | 4.26% | 4.88% |
| Mar 19, 2026 | 4.25% | 4.83% |
| Mar 20, 2026 | 4.39% | 4.96% |
| Mar 23, 2026 | 4.34% | 4.91% |
| Mar 24, 2026 | 4.39% | 4.94% |
| Mar 25, 2026 | 4.33% | 4.89% |
| Mar 26, 2026 | 4.42% | 4.93% |
| Mar 27, 2026 | 4.44% | 4.98% |
| Mar 30, 2026 | 4.35% | 4.91% |
| Mar 31, 2026 | 4.30% | 4.88% |
| Apr 1, 2026 | 4.33% | 4.91% |
| Apr 2, 2026 | 4.31% | 4.88% |
| Apr 3, 2026 | 4.35% | 4.91% |
| Apr 6, 2026 | 4.34% | 4.89% |
| Apr 7, 2026 | 4.33% | 4.90% |
| Apr 8, 2026 | 4.29% | 4.89% |
| Apr 9, 2026 | 4.29% | 4.90% |
| Apr 10, 2026 | 4.31% | 4.91% |
| Apr 13, 2026 | 4.30% | 4.90% |
| Apr 14, 2026 | 4.26% | 4.87% |
| Apr 15, 2026 | 4.29% | 4.89% |
| Apr 16, 2026 | 4.32% | 4.93% |
| Apr 17, 2026 | 4.26% | 4.88% |
| Apr 20, 2026 | 4.26% | 4.88% |
| Apr 21, 2026 | 4.30% | 4.89% |
| Apr 22, 2026 | 4.30% | 4.90% |
| Apr 23, 2026 | 4.34% | 4.92% |
| Apr 24, 2026 | 4.31% | 4.91% |
| Apr 27, 2026 | 4.35% | 4.94% |
| Apr 28, 2026 | 4.36% | 4.94% |
| Apr 29, 2026 | 4.42% | 4.98% |
| Apr 30, 2026 | 4.40% | 4.98% |
| May 1, 2026 | 4.39% | 4.97% |
| May 4, 2026 | 4.45% | 5.02% |
| May 5, 2026 | 4.43% | 4.98% |
| May 6, 2026 | 4.36% | 4.94% |
| May 7, 2026 | 4.41% | 4.97% |
| May 8, 2026 | 4.38% | 4.95% |
| May 11, 2026 | 4.42% | 4.98% |
| May 12, 2026 | 4.46% | 5.03% |
| May 13, 2026 | 4.46% | 5.03% |
| May 14, 2026 | 4.47% | 5.02% |
| May 15, 2026 | 4.59% | 5.12% |
| May 18, 2026 | 4.61% | 5.14% |
| May 19, 2026 | 4.67% | 5.18% |
| May 20, 2026 | 4.57% | 5.11% |
| May 21, 2026 | 4.57% | 5.10% |
| May 22, 2026 | 4.56% | 5.07% |
| May 26, 2026 | 4.50% | 5.03% |
| May 27, 2026 | 4.48% | 5.01% |
| May 28, 2026 | 4.45% | 4.98% |
| May 29, 2026 | 4.45% | 4.99% |
| Jun 1, 2026 | 4.47% | 4.99% |
| Jun 2, 2026 | 4.46% | 4.97% |
| Jun 3, 2026 | 4.49% | 4.99% |
| Jun 4, 2026 | 4.47% | 4.97% |
| Jun 5, 2026 | 4.55% | 5.01% |
| Jun 8, 2026 | 4.56% | 5.03% |
| Jun 9, 2026 | 4.53% | 5.01% |
| Jun 10, 2026 | 4.55% | 5.03% |
| Jun 11, 2026 | 4.45% | 4.95% |
| Jun 12, 2026 | 4.48% | 4.97% |
| Jun 15, 2026 | 4.47% | 4.97% |
| Jun 16, 2026 | 4.43% | 4.93% |
| Jun 17, 2026 | 4.49% | 4.93% |
| Jun 18, 2026 | 4.46% | 4.90% |
| Jun 22, 2026 | 4.51% | 4.95% |
| Jun 23, 2026 | 4.50% | 4.94% |
| Jun 24, 2026 | 4.41% | 4.86% |
| Jun 25, 2026 | 4.40% | 4.86% |
| Jun 26, 2026 | 4.38% | 4.87% |
| Jun 29, 2026 | 4.38% | 4.86% |
| Jun 30, 2026 | 4.44% | 4.91% |
| Jul 1, 2026 | 4.48% | 4.97% |
| Jul 2, 2026 | 4.49% | 4.98% |
| Jul 6, 2026 | 4.48% | 4.99% |
| Jul 7, 2026 | 4.55% | 5.05% |
| Jul 8, 2026 | 4.56% | 5.06% |
| Jul 9, 2026 | 4.54% | 5.05% |
| Jul 10, 2026 | 4.56% | 5.06% |
| Jul 13, 2026 | 4.62% | 5.10% |
| Jul 14, 2026 | 4.58% | 5.08% |
| Jul 15, 2026 | 4.55% | 5.08% |
| Jul 16, 2026 | 4.57% | 5.09% |
| Jul 17, 2026 | 4.55% | 5.06% |
| Jul 20, 2026 | 4.60% | 5.11% |
| Jul 21, 2026 | 4.63% | 5.13% |
| Jul 22, 2026 | 4.67% | 5.15% |
| Jul 23, 2026 | 4.71% | 5.17% |
| Jul 24, 2026 | 4.69% | 5.16% |
| Jul 27, 2026 | 4.65% | 5.12% |
| Jul 28, 2026 | 4.61% | 5.09% |
| Jul 29, 2026 | 4.67% | 5.20% |
| Jul 30, 2026 | 4.68% | 5.21% |
| Jul 31, 2026 | 4.75% | 5.27% |
| Aug 3, 2026 | 4.70% | 5.23% |
| Aug 4, 2026 | 4.63% | 5.18% |
| Aug 5, 2026 | 4.63% | 5.17% |
| Aug 6, 2026 | 4.69% | 5.22% |
| Aug 7, 2026 | 4.65% | 5.19% |
| Aug 10, 2026 | 4.72% | 5.25% |
| Aug 11, 2026 | 4.70% | 5.24% |
| Aug 12, 2026 | 4.68% | 5.24% |
| Aug 13, 2026 | 4.63% | 5.21% |
| Aug 14, 2026 | 4.68% | 5.25% |
| Aug 17, 2026 | 4.72% | 5.31% |
| Aug 18, 2026 | 4.71% | 5.28% |
| Aug 19, 2026 | 4.65% | 5.19% |
| Aug 20, 2026 | 4.69% | 5.23% |
| Aug 21, 2026 | 4.74% | 5.27% |
| Aug 24, 2026 | 4.70% | 5.23% |
| Aug 25, 2026 | 4.64% | 5.17% |
| Aug 26, 2026 | 4.66% | 5.18% |
| Aug 27, 2026 | 4.67% | 5.19% |
| Aug 28, 2026 | 4.73% | 5.22% |
| Aug 31, 2026 | 4.75% | 5.25% |
| Sep 1, 2026 | 4.79% | 5.27% |
| Sep 2, 2026 | 4.79% | 5.27% |
| Sep 3, 2026 | 4.77% | 5.25% |
| Sep 4, 2026 | 4.78% | 5.24% |
| Sep 8, 2026 | 4.80% | 5.25% |
| Sep 9, 2026 | 4.83% | 5.28% |
| Sep 10, 2026 | 4.95% | 5.37% |
| Sep 11, 2026 | 4.96% | 5.35% |
| Sep 14, 2026 | 4.97% | 5.34% |
| Sep 15, 2026 | 5.00% | 5.36% |
| Sep 16, 2026 | 5.01% | 5.35% |
| Sep 17, 2026 | 4.94% | 5.29% |
| Sep 18, 2026 | 5.01% | 5.34% |
| Sep 21, 2026 | 4.96% | 5.29% |
| Sep 22, 2026 | 4.96% | 5.29% |
| Sep 23, 2026 | 5.11% | 5.40% |
| Sep 24, 2026 | 5.18% | 5.47% |
| Sep 25, 2026 | 5.17% | 5.49% |
| Sep 28, 2026 | 5.24% | 5.56% |
| Sep 29, 2026 | 5.26% | 5.59% |
| Sep 30, 2026 | 5.29% | 5.64% |
| Oct 1, 2026 | 5.24% | 5.61% |
| Oct 2, 2026 | 5.28% | 5.63% |
| Oct 5, 2026 | 5.31% | 5.66% |
| Oct 6, 2026 | 5.27% | 5.64% |
| Oct 7, 2026 | 5.28% | 5.67% |
| Oct 8, 2026 | 5.22% | 5.60% |
| Oct 9, 2026 | 5.24% | 5.60% |
| Oct 13, 2026 | 5.21% | 5.56% |
| Oct 14, 2026 | 5.19% | 5.52% |
| Oct 15, 2026 | 5.10% | 5.43% |
| Oct 16, 2026 | 5.09% | 5.43% |
| Oct 19, 2026 | 5.15% | 5.48% |
| Oct 20, 2026 | 5.12% | 5.42% |
| Oct 21, 2026 | 5.13% | 5.42% |
| Oct 22, 2026 | 4.96% | 5.29% |
| Oct 23, 2026 | 5.00% | 5.33% |
The turbulence eased, but the episode exposed how quickly a policy announcement could turn into a funding problem. The New York Fed found that market liquidity recovered; by early 2026 it was the strongest since 2021. That recovery preceded the war with Iran and the renewed pressure of 2026.4
The yield is the return investors demand at the current market price. When existing bond prices fall, yields rise. Washington feels the higher rates as it sells new debt and replaces debt coming due. The coupon on every old bond does not suddenly change.
The borrowing bill behind the deal.
The federal government spent $7.40 trillion in fiscal 2026 and took in $5.40 trillion. The resulting $1.99 trillion deficit was about $217 billion larger than the year before. Net interest alone consumed nearly one dollar in every five collected.3
Trump did not inherit a balanced budget. But the choices made by his party deepen the borrowing requirement. The Congressional Budget Office put the added deficits from the 2025 Republican tax-and-spending law at $4.7 trillion over 2026–2035, including its economic and interest effects.5
A trillion dollars, just in interest
The tax law’s arithmetic
CBO’s estimate for 2025–2034, before economic feedback and interest costs.
Added to primary deficits.
Reduction in primary deficits.
More borrowing before the interest bill.
The ten-year periods differ: this breakdown uses 2025–2034; the broader $4.7 trillion estimate above uses 2026–2035.5
The program cuts did not pay for the tax package. CBO’s conventional estimate added another $718 billion in debt service over 2025–2034. The political bargain reduced support through health and other programs while leaving a much larger hole on the revenue side.5
Borrowing is how the government carries that hole forward. Interest then competes with the services and investments future budgets could otherwise support. The damage can accumulate without a single spectacular failed auction.
$5,000 for you. A trillion-dollar question for Treasury.
In Dallas on September 9, Trump made the borrowing problem an election promise. Every adult American citizen would get $5,000, he told the Republican convention, if his party won both chambers of Congress. The money was to be spent in the United States.6
The White House promoted the payment the following day as a dividend from America’s success. Voters were being offered a personal reward, attached to a party-political condition.8
The Tax Foundation estimated the unrestricted proposal at $1.25 trillion, using 250 million voting-eligible adults as its population proxy. Its estimate of additional net tariff revenue for 2027 was $125 billion. The one-time payout would consume ten times that projected annual revenue.7
The check and the tariff revenue
The pledge still needs a funding plan that closes that gap. Repeating the tariff claim does not produce the missing revenue. A government already borrowing nearly $2 trillion a year would have to raise more money, cut other spending, narrow the promise or add to the debt.
The conflict comes home through prices.
The war with Iran put another cost into the system. In September, gasoline prices jumped 9.1% in a month, accounting for more than half the increase in the overall Consumer Price Index. Annual inflation reached 3.7%.9
The International Energy Agency’s October report described renewed attacks on infrastructure and tankers threatening the recovery of Gulf exports. For American households, the conflict arrived through fuel prices. For bond investors, it also raised the question of how long inflation would keep interest rates high.11
The war bill keeps growing.
Reuters reports that Pentagon data put the Iran war’s cost above $47 billion, roughly a quarter higher than its July estimate. The latest spending report and Trump’s remarks Reuters’ report

At its September meeting, the Federal Reserve raised its target rate by a quarter point to 3.75–4%. The minutes described persistent inflation, energy shocks and investors expecting tighter policy. They also recorded concern about heavy borrowing for artificial-intelligence infrastructure. Washington was competing for financing in a more expensive market.10
Trump’s response to high mortgage rates on October 7 was to accuse the Fed’s board of wanting the country to do badly. Bessent pointed to the energy shock and predicted relief after the conflict. Homebuyers still had to deal with the rate in front of them.12
This is where the promises collide. Tariffs raise costs, war disrupts energy supplies, and a government increasing its borrowing wants lenders to accept less. The Fed’s September record shows investors weighing those pressures together. A presidential attack on the central bank does not remove them.10
Bessent tries to steady the market.
Scott Bessent’s job is to sell America’s debt while serving a president who keeps adding to the promises. In August, Treasury announced that maximum purchases of older, longer-dated bonds would rise from $2 billion to at least $4 billion per operation. The department described the expansion as liquidity support.13
The September 10 operation accepted $5.187 billion in face value of bonds against a $6 billion ceiling. Dealers had offered $10.489 billion in face value. The results show the debt Treasury agreed to retire, security by security.14
Five days later, Democratic Rep. Jim Himes pressed Bessent about yields rising despite the intervention. Bessent defended the operation as a success and argued that the outcome might otherwise have been worse. The exchange left the question of its measurable effect hanging.15

Buybacks can make older bonds easier to trade and help Treasury manage its cash. They do not erase the government’s spending commitments or its need to finance a deficit. Buying back one security while issuing another changes the debt being traded; the budget still has to be funded.16
The political attraction is obvious: a visible intervention, an announcement that Washington is taking action. The harder test is whether investors can buy and sell smoothly, and what taxpayers ultimately pay to borrow. Those questions survive the press release.
A fragile trade beneath the politics.
The market beneath these announcements is increasingly dependent on investors who buy government debt with borrowed money. Dallas Fed researchers estimated that hedge funds’ net borrowing through repurchase agreements reached about $1.8 trillion at the end of 2025. Growing Treasury supply had increased the reliance on these leveraged buyers.17
For a hedge fund, a tiny price difference between related securities can become profitable when the position is large enough and financing is cheap. The risk runs the other way too. If lenders demand more collateral or financing tightens, traders can be pushed into selling precisely when the market is already under strain.17
$60 billion unwound in the tariff turmoil
Federal Reserve research found that roughly $60 billion of one leveraged strategy, the Treasury swap-spread trade, unwound rapidly after the April 2025 tariff announcements. Positions later recovered. The episode showed how a policy shock could travel through borrowed money into a much bigger market move.18
The same research put hedge funds’ Treasury cash-futures basis trade at about $830 billion in September 2025. These strategies help absorb government debt in ordinary trading. Their scale also means that Treasury-market resilience depends on the funding behind the trade, not simply on whether the United States can pay a bond at maturity.18

The bill lands in ordinary lives.
For a household shopping for a home, the bond-market story is already in the offer. Freddie Mac’s average 30-year fixed mortgage rate was 7.32% on October 22, compared with 6.19% in the equivalent weekly survey a year earlier.19
On the same $300,000 loan, that difference adds about $225 a month in principal and interest, or roughly $2,704 a year. It arrives before property taxes, insurance and maintenance. The calculation below uses the two published rates and lets you change the loan amount.
October 28: no relief from the Fed.
The Fed left its target range at 3.75%–4%, six days before the election. Inflation remained elevated; two dissenters wanted rates raised another quarter point. Borrowers got no rate cut, and Trump got no late boost to his economic pitch. Read the decision The economic picture The Midterm Brief
October 29: growth rises, inflation stays in the way.
The latest GDP release puts third-quarter growth at a 3.4% annualized rate. September PCE inflation was 3.6% over the year. After the Fed’s October 28 hold, these figures leave persistent price pressure in the borrowing story. GDP release Inflation release The household figures The Midterm Brief
The borrowing problem survives election day.
Investors interviewed by Reuters are looking past November 3 to the financing that will follow it. Federal debt has passed $40 trillion, while the annual deficit is running near $2 trillion, roughly 6% of the economy. Whoever wins Congress inherits a government already borrowing on an extraordinary scale.
The immediate political calendar includes a December 11 funding deadline. Beyond it sit the spending, tax and interest bills that Treasury must finance. A change in congressional control can alter those decisions; it does not remove the existing borrowing requirement.
The cost facing new homebuyers
View the data
| Date | 30-year fixed mortgage |
|---|---|
| Jan 2, 2025 | 6.91% |
| Jan 9, 2025 | 6.93% |
| Jan 16, 2025 | 7.04% |
| Jan 23, 2025 | 6.96% |
| Jan 30, 2025 | 6.95% |
| Feb 6, 2025 | 6.89% |
| Feb 13, 2025 | 6.87% |
| Feb 20, 2025 | 6.85% |
| Feb 27, 2025 | 6.76% |
| Mar 6, 2025 | 6.63% |
| Mar 13, 2025 | 6.65% |
| Mar 20, 2025 | 6.67% |
| Mar 27, 2025 | 6.65% |
| Apr 3, 2025 | 6.64% |
| Apr 10, 2025 | 6.62% |
| Apr 17, 2025 | 6.83% |
| Apr 24, 2025 | 6.81% |
| May 1, 2025 | 6.76% |
| May 8, 2025 | 6.76% |
| May 15, 2025 | 6.81% |
| May 22, 2025 | 6.86% |
| May 29, 2025 | 6.89% |
| Jun 5, 2025 | 6.85% |
| Jun 12, 2025 | 6.84% |
| Jun 18, 2025 | 6.81% |
| Jun 26, 2025 | 6.77% |
| Jul 3, 2025 | 6.67% |
| Jul 10, 2025 | 6.72% |
| Jul 17, 2025 | 6.75% |
| Jul 24, 2025 | 6.74% |
| Jul 31, 2025 | 6.72% |
| Aug 7, 2025 | 6.63% |
| Aug 14, 2025 | 6.58% |
| Aug 21, 2025 | 6.58% |
| Aug 28, 2025 | 6.56% |
| Sep 4, 2025 | 6.50% |
| Sep 11, 2025 | 6.35% |
| Sep 18, 2025 | 6.26% |
| Sep 25, 2025 | 6.30% |
| Oct 2, 2025 | 6.34% |
| Oct 9, 2025 | 6.30% |
| Oct 16, 2025 | 6.27% |
| Oct 23, 2025 | 6.19% |
| Oct 30, 2025 | 6.17% |
| Nov 6, 2025 | 6.22% |
| Nov 13, 2025 | 6.24% |
| Nov 20, 2025 | 6.26% |
| Nov 26, 2025 | 6.23% |
| Dec 4, 2025 | 6.19% |
| Dec 11, 2025 | 6.22% |
| Dec 18, 2025 | 6.21% |
| Dec 24, 2025 | 6.18% |
| Dec 31, 2025 | 6.15% |
| Jan 8, 2026 | 6.16% |
| Jan 15, 2026 | 6.06% |
| Jan 22, 2026 | 6.09% |
| Jan 29, 2026 | 6.10% |
| Feb 5, 2026 | 6.11% |
| Feb 12, 2026 | 6.09% |
| Feb 19, 2026 | 6.01% |
| Feb 26, 2026 | 5.98% |
| Mar 5, 2026 | 6.00% |
| Mar 12, 2026 | 6.11% |
| Mar 19, 2026 | 6.22% |
| Mar 26, 2026 | 6.38% |
| Apr 2, 2026 | 6.46% |
| Apr 9, 2026 | 6.37% |
| Apr 16, 2026 | 6.30% |
| Apr 23, 2026 | 6.23% |
| Apr 30, 2026 | 6.30% |
| May 7, 2026 | 6.37% |
| May 14, 2026 | 6.36% |
| May 21, 2026 | 6.51% |
| May 28, 2026 | 6.53% |
| Jun 4, 2026 | 6.48% |
| Jun 11, 2026 | 6.52% |
| Jun 18, 2026 | 6.47% |
| Jun 25, 2026 | 6.49% |
| Jul 2, 2026 | 6.43% |
| Jul 9, 2026 | 6.49% |
| Jul 16, 2026 | 6.55% |
| Jul 23, 2026 | 6.58% |
| Jul 30, 2026 | 6.66% |
| Aug 6, 2026 | 6.69% |
| Aug 13, 2026 | 6.67% |
| Aug 20, 2026 | 6.65% |
| Aug 27, 2026 | 6.66% |
| Sep 3, 2026 | 6.71% |
| Sep 10, 2026 | 6.76% |
| Sep 17, 2026 | 6.95% |
| Sep 24, 2026 | 7.03% |
| Oct 1, 2026 | 7.28% |
| Oct 8, 2026 | 7.40% |
| Oct 15, 2026 | 7.40% |
| Oct 22, 2026 | 7.32% |
Same loan. More interest.
Illustrative new 30-year fixed loan at Freddie Mac’s weekly average rates. Principal and interest only; excludes taxes, insurance and fees. Existing fixed-rate mortgages keep their contracted rate.
Mortgages do not track Treasury yields penny for penny. The rate includes the cost of guaranteeing and servicing the loan, lenders’ margins and the risk that borrowers refinance when rates fall. The Boston Fed’s research traces those extra costs. That helps explain why a small improvement in Treasuries may not immediately rescue a buyer’s budget.20
The federal bill works over a longer horizon. In September, CBO projected debt held by the public rising from about 101% of the economy in 2026 to 175% in 2056 under current law. Annual deficits keep adding to the stock of debt; interest keeps adding to the cost of carrying it.21
Trump can promise a check, unveil a tariff chart and berate the Fed. The government still needs buyers for its debt, and those buyers set a price. The tax law, the war and the election pledges do not disappear when the speech ends. They return in the next auction, the next budget and the next mortgage offer.
Sources, recordings and data.
Reporting checked October 24, 2026. Treasury yields are daily par-curve observations through October 23; mortgage rates are Freddie Mac weekly averages through October 22. Federal budget charts use completed fiscal-year actuals. Policy cost estimates retain their stated time periods.
- Trump’s exchange with reporters at Joint Base Andrews Government Publishing Office · August 21, 2026
- Daily Treasury par yield curve rates U.S. Treasury · January 2, 2025–October 23, 2026
- Monthly Treasury Statement, Tables 1 and 9 U.S. Treasury · Fiscal year ended September 30, 2026
- Treasury Market Liquidity Since April 2025 Federal Reserve Bank of New York · April 2, 2026; observations through February 27
- The Budget and Economic Outlook: 2026 to 2036, Appendix A Congressional Budget Office · February 2026
- Trump’s remarks at the Republican midterm convention in Dallas Government Publishing Office · September 9, 2026
- No, Tariffs Can’t Fund $5,000 Dividends to All Adult US Citizens Tax Foundation · September 10, 2026
- Trump Dividend: America Is Winning, and Americans Should Win With It White House · September 10, 2026
- Consumer Price Index: September 2026 Bureau of Labor Statistics · October 14, 2026
- Minutes of the September 15–16 meeting Federal Reserve · October 7, 2026
- Oil Market Report, October 2026 International Energy Agency · October 2026
- Trump says Federal Reserve Board would like to see the country do badly Reuters · October 7, 2026
- Increased sizes of long-end liquidity support buybacks U.S. Treasury · August 19, 2026
- Treasury debt buyback operation results Bureau of the Fiscal Service · September 10, 2026
- Bessent calls bond buybacks a success despite climb in yields Reuters · September 15, 2026
- Treasury buybacks: frequently asked questions Bureau of the Fiscal Service · Accessed October 24, 2026
- Rising hedge fund leverage affects monetary policy implementation Federal Reserve Bank of Dallas · May 28, 2026; data through December 2025
- Decomposing Hedge Funds’ U.S. Treasury Exposures Federal Reserve · June 22, 2026; data through September 2025
- Primary Mortgage Market Survey Freddie Mac · Weekly observations through October 22, 2026
- Why Mortgage Rates Exceed Treasury Yields Federal Reserve Bank of Boston · May 19, 2026
- Projections of Deficits and Debt Under Alternative Scenarios for Interest Rates and the Budget Congressional Budget Office · September 24, 2026
- Receipts and outlays by function of government U.S. Treasury · Completed fiscal years 2019–2026