The 47 Files · Investigation
The Big Beautiful Bill?
The tax breaks.
The human cost.
Trump signed it with a flourish. The consequences arrive in tax returns, hospital budgets and empty grocery carts. Follow the votes, the money and the people left to pay.
Jump to a section
01 · The signing
A holiday victory. A much longer reckoning.
Donald Trump chose the Fourth of July for the signing. Republican lawmakers gathered around him at the White House, and House Speaker Mike Johnson presented him with the gavel used to pass the bill. Trump had demanded a legislative victory in time for the holiday. His party delivered.
The celebration was over in an afternoon. The law will reorder federal taxes, health coverage, food assistance, student borrowing and immigration enforcement for years. Its central bargain is already visible: lasting tax advantages for businesses and wealthy estates, temporary deductions built around campaign slogans, and deep reductions in programs used by people with far less money.
By November 2026, millions of taxpayers had claimed the new deductions. Food-assistance enrollment had fallen sharply. Federal support for clean-energy purchases had been cut back. Other consequences were still approaching: a nationwide Medicaid work-reporting requirement, new state food-assistance bills and tighter hospital financing. The rollout puts the popular benefits and the most disruptive cuts on different clocks.
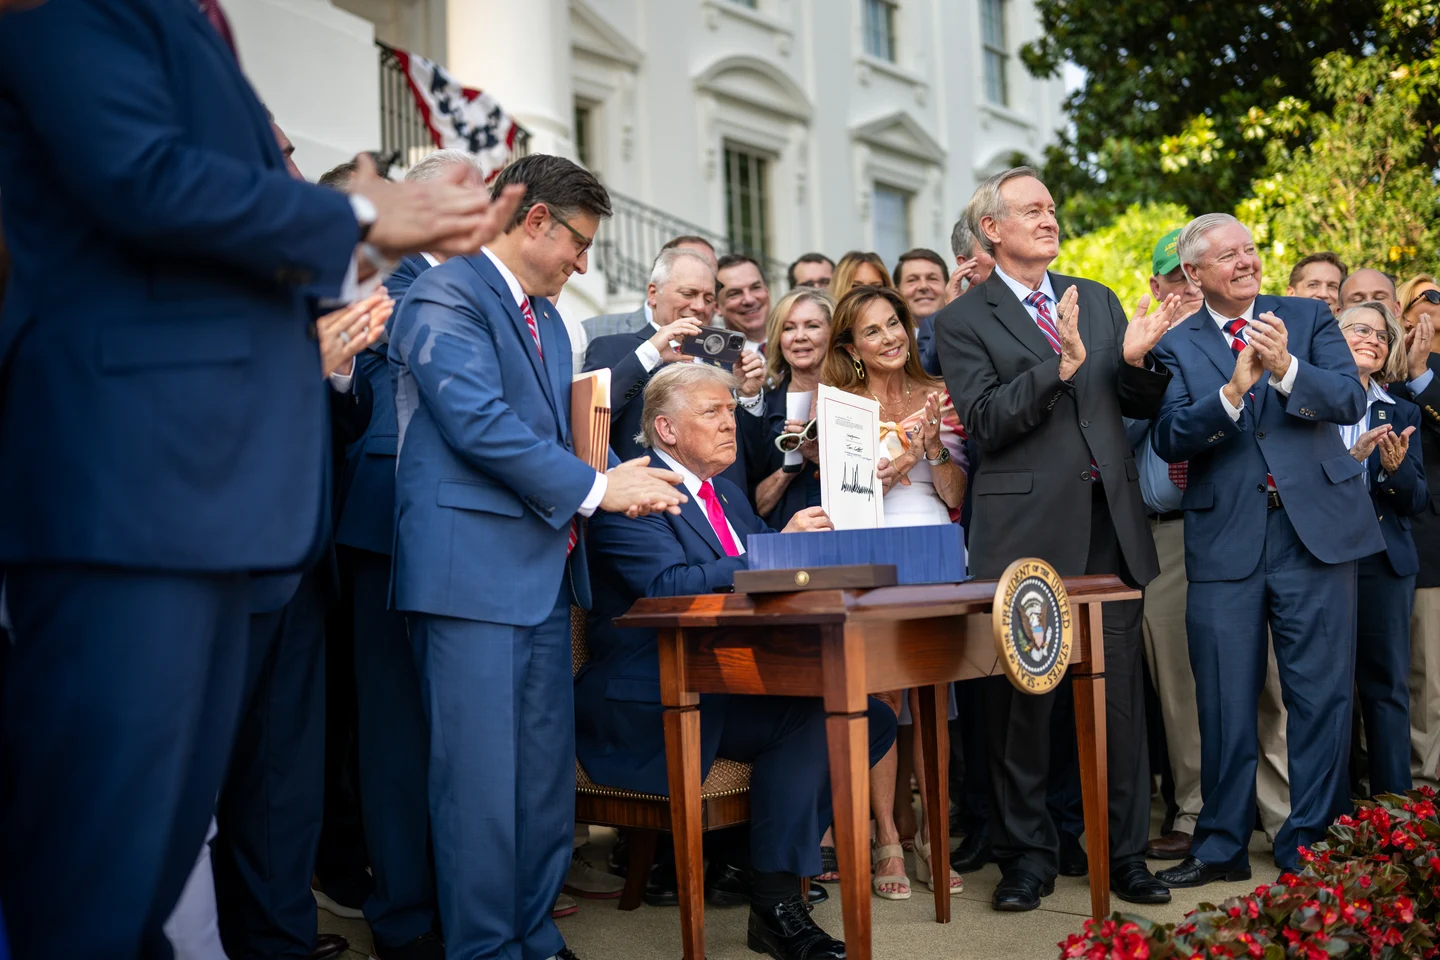
FOX 5 DC · July 4, 2025. Open the original recording
02 · The vote
One party passed it. Five Republicans broke ranks.
The law belongs to the Republican Party. Every vote in favor in the House and Senate came from a Republican. Democrats opposed it unanimously, joined in the Senate by the two independents who caucus with them. The majorities were narrow enough for a handful of lawmakers to have stopped it.
House · July 3, 2025
218–214
Final agreement to the Senate’s version
| Party | Yes | No |
|---|---|---|
| Republican | 218 | 2 |
| Democratic | 0 | 212 |
Senate · July 1, 2025
50–50
JD Vance broke the tie in favor
| Party | Yes | No |
|---|---|---|
| Republican | 50 | 3 |
| Democratic | 0 | 45 |
| Independent | 0 | 2 |
Gold: yes. Blue: no. The recorded Senate result was 51–50 including Vance. Figures cover final passage, not earlier procedural votes.
The five Republicans who said no
In the House, Brian Fitzpatrick of Pennsylvania and Thomas Massie of Kentucky broke ranks. Fitzpatrick said the Senate’s Medicaid changes crossed a line. He had supported the House’s earlier version; he would not support this one.
In the Senate, the dissenters were Susan Collins of Maine, Thom Tillis of North Carolina and Rand Paul of Kentucky. Collins cited the damage to low-income families, rural hospitals and nursing homes. Tillis warned that North Carolina stood to lose coverage for hundreds of thousands of people. Their objections put the Medicaid cuts inside the Republican argument, well before the law’s consequences reached a renewal notice or hospital ledger.
Vance supplied the final vote. Johnson delivered the House. Their names belong beside the president’s on the political record of what followed.
03 · The tax bargain
Permanent at the top. Temporary on the stump.
The enduring achievement was to lock in much of Trump’s 2017 tax law before it expired. The 2025 law preserved individual rates and the larger standard deduction, made the 20 percent deduction for qualifying pass-through business income permanent, and restored favorable treatment for business investment and domestic research.
It also raised the estate-tax exemption to $15 million per person in 2026, indexed thereafter. For wealthy families planning what to pass on, that is a durable advantage. The headline deductions for tips, overtime, seniors and car-loan interest, by contrast, run through 2028.
The child tax credit rose to $2,200, with inflation indexing. The cap on state and local tax deductions increased temporarily to $40,000 for 2025, subject to income limits. These changes reach different households in very different ways. A tax deduction is most useful to someone who has taxable income to reduce; a family losing food assistance cannot spend an estate-tax exemption.
CBO projection · 2026–2034
The biggest gain goes to the top.
Average annual change per household, in 2025 dollars
The slogan on the campaign trail, the rule on the return
The tips deduction covers up to $25,000 in qualified tips. The overtime deduction is capped at $12,500, or $25,000 for a joint return, and applies to the legally required premium above ordinary pay. For time-and-a-half work, that generally means the extra half, not the whole paycheck. Social Security and Medicare payroll taxes still apply.
The additional deduction for people 65 and older is up to $6,000 each, with income phaseouts. It does not repeal the tax rules for Social Security benefits. The car-loan provision allows up to $10,000 of qualifying interest on eligible new vehicles assembled in the United States, also with income limits.
What has actually reached tax returns
Treasury reported in June 2026 that more than 29 million filers had claimed the overtime deduction, averaging over $3,100 in deducted income. More than 7.5 million had claimed the tips deduction, averaging over $7,000. Those are deductions, not refund checks of the same size. A $3,100 deduction at a 22 percent marginal rate would reduce federal income tax by $682, before other interactions.
The tax relief has reached working households. The distributional question is what remains after benefit cuts and the rest of the law are included. CBO’s analysis puts the largest dollar gains at the top and a net loss at the bottom.
04 · Health care
The cuts reach the waiting room.
The Medicaid cuts do not arrive as one canceled program. They arrive through eligibility checks, narrower access, restrictions on how states finance care and limits on what hospitals can receive. That makes the damage harder to see in a single announcement and harder for patients to avoid.
CRS, drawing on CBO estimates of the enacted law. The coverage estimate compares with the January 2025 baseline.
Medicaid accounts for about $911 billion of the federal spending reduction over the decade, according to KFF’s compilation of the enacted provisions. Its coverage changes account for an estimated 7.5 million of the additional uninsured. Medicaid pays for much more than a doctor’s visit: it supports long-term care, disability services and the institutions that keep rural health systems operating.
From October 1, 2026, the law narrowed eligibility for some people lawfully in the country, including refugees and people granted asylum who do not have a qualifying alternative status. Tighter limits on provider taxes and state-directed payments phase in later, reducing the financing states use to support hospitals and other providers.
Coverage tied to a monthly test
The national deadline for states to implement the new Medicaid work requirements is January 1, 2027. Many adults covered through the expansion must demonstrate 80 hours a month of work or other qualifying activity, unless exempt. Nebraska began its rollout on May 1, 2026.
The practical test extends beyond whether someone works. It includes whether the state can verify the hours, whether a person knows an exemption applies, and whether paperwork reaches the right office on time. People with unstable schedules and interrupted employment have the most to navigate.
A rescue fund beside a much larger withdrawal
Congress created a $50 billion Rural Health Transformation Program for 2026–2030. It is a five-year allocation beside health-financing changes that extend well beyond it. Hospitals must plan around both. The American Hospital Association warned that the law would reduce coverage and put access to care at risk, particularly for vulnerable communities.
The law also delayed the federal nursing-home minimum-staffing rule until 2034. The administration subsequently rescinded that rule separately. For families choosing a nursing home, the promise of a stronger federal staffing floor has receded.
Reproductive care: the ban expired, the disruption did not simply disappear
The law’s one-year restriction on federal Medicaid payments to certain reproductive-health providers, chiefly Planned Parenthood, expired on July 3, 2026. KFF’s subsequent review shifted the focus to state decisions. The expiration did not automatically reopen clinics.
Planned Parenthood reported nearly 30 health-center closures during the funding squeeze, alongside fewer contraceptive-pill packs and breast exams, according to AP’s July 6 reporting. The lost services extended well beyond abortion care.
05 · Food assistance
Fewer people at the checkout.
For food assistance, the first year has produced a striking number: 5.5 million fewer people receiving SNAP between July 2025 and July 2026. The Center on Budget and Policy Priorities calculated that decline from USDA data. Enrollment fell 13 percent, to 36.1 million.
Recorded enrollment · USDA data analyzed by CBPP
5.5 million fewer people on SNAP.
In 28 states with available data, the number of children receiving assistance fell by 1.5 million. CBPP found that declines had begun before the law but accelerated in almost all states afterward. The pattern raises a question that the administration’s language about efficiency leaves unanswered: how many eligible families are falling out of the system?
The law expanded the reach of SNAP’s work-related time limit, removed several exemptions and restricted eligibility for some lawfully present immigrants. It also changed who pays. The federal share of administrative costs fell from 50 percent to 25 percent in October 2026. Beginning in October 2027, many states face a new obligation to fund between 5 and 15 percent of benefits, tied to payment-error rates.
That formula can put states under pressure to cut costs or make enrollment harder. Payment-error rates measure mistakes in benefit amounts and eligibility determinations, including underpayments. They are not a measure of fraud.
The agriculture title makes the priorities especially clear. CRS estimated a $186.65 billion reduction in nutrition spending over 2025–2034 alongside $65.69 billion in additional spending elsewhere in agriculture. Farm support was expanded while food assistance was cut. Calling the entire title a saving conceals who gives up the money.
06 · Education
The cost of a qualification moves onto the borrower.
The new borrowing limits reach people at a moment when they have already chosen a profession and often secured a place to study. Starting in July 2026, the law phases out new Graduate PLUS borrowing, with exceptions for some existing students, and imposes new limits on graduate and parent loans.
Ordinary graduate borrowers face a $20,500 annual federal limit and a $100,000 aggregate limit. Qualifying professional students have higher limits: $50,000 annually and $200,000 in aggregate. When tuition and living costs exceed the federal allowance, students must find savings, scholarships or private credit, or change their plans. Private lenders can price the risk into the loan; the student carries it.
The Department of Education’s new Repayment Assistance Plan links payments to income, with a $10 monthly floor and up to 30 years before forgiveness. It includes an unpaid-interest waiver for qualifying payments. The transition also ends access to older income-driven arrangements on the law’s timetable. The consequences depend on a borrower’s income, family circumstances and existing loans; a lower payment today can sit beside a longer repayment horizon.
The professional-degree dispute, Workforce Pell and school choice
The administration’s narrow definition of a professional student provoked litigation from programs and professional groups. A June 29, 2026 court order temporarily changed which students could access the higher limits. For nursing and other affected programs, access to the higher limits is now bound up in that court fight.
Workforce Pell extends grants to qualifying short-term training programs. Its test will be whether those courses deliver useful credentials and earnings, rather than simply a new source of public payments to providers.
Beginning in 2027, a separate federal credit offers up to $1,700 for qualifying donations to scholarship-granting organizations in participating states. It directs federal tax support toward a school-choice system whose reach depends on state participation and the organizations distributing the scholarships.
07 · Energy and climate
A shorter runway for a cleaner economy.
The clean-energy provisions pulled away support that households and companies had been using to plan purchases and construction. Federal credits for buying new and used electric vehicles ended after September 30, 2025. Major home-energy credits ended after 2025.
Wind and solar projects face accelerated deadlines: generally, they must begin construction by July 4, 2026 or be placed in service by the end of 2027 to retain the affected credits, with additional restrictions. Businesses making investments over many years received a compressed timetable and a new set of financing risks.
The retreat is appearing in investment records
The Clean Investment Monitor recorded $17 billion in cancellations of clean-electricity and industrial-decarbonization projects in the second quarter of 2026. Clean manufacturing investment was 24 percent below a year earlier. These are recorded investment developments across a sector also exposed to tariffs, demand changes and other policy decisions.
The monitor still recorded $75 billion in total clean-energy and transportation investment that quarter, up 4 percent from a year earlier. The weakness was concentrated: construction and manufacturing pipelines were being cut back even while money continued to flow into the broader market.
Rhodium Group projection · 2035
Higher household energy costs.
+$78 to +$192 a yearRhodium’s assessment projected 53–59 percent less new clean-power capacity over 2025–2035 than under its prior-policy baseline. The result is more than a lost climate target. It affects the supply of electricity, the cost of meeting rising demand and the jobs tied to building that capacity.
08 · Immigration and defense
There was money for this.
Fiscal restraint stopped well short of the deportation machinery. The law provided roughly $170 billion across Homeland Security programs, including an extraordinary expansion of Immigration and Customs Enforcement funding.
Those multi-year appropriations give ICE about $74.85 billion for detention and operations. That money pays for capacity to hold and remove many more people. Other Homeland Security provisions finance border barriers, personnel and related operations.
Defense received roughly $150 billion in additional funding, including missile defense, shipbuilding, munitions and nuclear capabilities. Congress committed that money while cutting the domestic programs elsewhere in the package.
09 · The federal ledger
The tax cuts leave a borrowing bill.
The cuts did not pay for the package. In its February 2026 outlook, CBO estimated that the law would increase deficits by $4.7 trillion over 2026–2035, including added interest costs and economic effects.
CBO projection · fiscal years 2026–2035
$4.7 trillionAdded to cumulative federal deficits.
CBO projected that the law would boost growth in 2026. It also projected higher interest rates and borrowing costs. In the agency’s calculations, those economic effects slightly increased the deficit overall. The tax cuts had not become self-financing because the economy was expected to grow faster.
The same law raised the statutory debt ceiling by $5 trillion, expanding the government’s legal borrowing authority.
The government must borrow the difference. Interest payments then compete with future budgets, long after the signing ceremony and after some of the temporary deductions have expired.
10 · Inside the other titles
The provisions outside the spotlight.
The law runs across far more of government than its tax slogans suggest. Several less prominent provisions change who receives public support, who pays new charges and how much capacity regulators retain.
Housing and investment zones
The law expands the Low-Income Housing Tax Credit and changes the financing rules for qualifying developments. It also renews and reshapes Opportunity Zones, which offer tax advantages for investment in designated areas. The housing test is additional affordable homes delivered; the investment-zone test is whether the tax benefit reaches existing communities as well as investors. The law also rescinds funds from the Green and Resilient Retrofit Program for assisted housing.
A smaller ceiling for the consumer watchdog
The Consumer Financial Protection Bureau’s statutory funding cap falls from 12 percent to 6.5 percent of its specified, inflation-adjusted Federal Reserve operating-expense base. That narrows the resources available to the agency responsible for policing consumer-finance abuses. It is a change to the funding ceiling, separate from the administration’s other efforts to curtail the bureau.
Aviation, NASA and spectrum
The commerce provisions include $12.5 billion for air-traffic-control modernization and roughly $10 billion for NASA, alongside changes to spectrum-auction authority. The money promises new equipment and missions, with delivery still unfolding. Aviation, space, health care and food assistance were all bound to the same party-line vote.
Public lands, fossil fuels and environmental programs
The enacted law expands opportunities for oil, gas and coal leasing, changes royalties and other terms, and cancels or rescinds several clean-energy and environmental programs. The proposed broad public-land selloff debated during negotiations did not become part of the final law. The enacted leasing changes are substantial enough to examine on their own.
New charges on remittances and limits on gambling losses
From January 1, 2026, a 1 percent excise tax applies to certain remittance transfers funded with cash, money orders, cashier’s checks and similar instruments. It does not apply to every transfer abroad. The design places the charge on particular ways people send money, including methods used by people without conventional banking access.
The law also limits the deduction for gambling losses to 90 percent from 2026, subject to the other deduction rules. A person whose eligible winnings and losses balance can therefore face taxable gambling income even without an overall gambling profit.
Trump Accounts and the child savings pilot
The law establishes tax-advantaged accounts for children and a $1,000 federal pilot contribution for eligible U.S.-citizen children born in 2025–2028. Treasury reported more than 5.5 million accounts opened by June 2026, with 1.4 million eligible for the pilot contribution. The eventual value depends on investment returns, fees and further contributions. Families able to add more money start with an advantage.
11 · The implementation calendar
The consequences keep coming.
The law’s political life and its administrative life run at different speeds. The tax slogans were ready for the 2026 campaign. Some of the deepest adjustments to health financing and state budgets lie beyond it.
- July 4, 2025
The law is signed. Several tax provisions apply to the 2025 tax year.
- September–December 2025
Vehicle credits end after September 30; major home-energy credits end after December 31.
- May–July 2026
Nebraska begins Medicaid work requirements. New federal student-loan rules begin. The one-year federal Planned Parenthood restriction expires.
- October 2026
The federal share of SNAP administration falls. Medicaid eligibility narrows for certain lawfully present immigrants.
- January 2027
The national Medicaid work-requirement deadline arrives. The school-choice donation credit begins.
- October 2027 onward
New state SNAP benefit costs begin for many states; major hospital-financing changes phase in over subsequent years.
- End of 2028
The tips, overtime, senior and qualifying car-interest deductions are scheduled to expire.
- 2034–2035
The main coverage and fiscal forecasts reach their endpoints. These are projection years, not outcomes already recorded.
The question behind the bill’s name is no longer whether Trump could force it through Congress. He did. It is what survives when a taxpayer’s deduction expires, a state has to find the money for food assistance, or a hospital has to operate with less support. Those consequences will outlast the photograph.
12 · Follow the evidence
The law, the votes and the underlying record.
Reporting and implementation reviewed through November 3, 2026. Figures use the enacted law, not discarded House or Senate proposals. Each forecast retains its period and source date; later implementation and court decisions are identified in the relevant section.
- Public Law 119-21: the enacted textCongress / Government Publishing Office
- The White House’s case for the lawWhite House · July 4, 2025
- Signing ceremony: official transcriptGovernment Publishing Office · July 4, 2025
- Final House vote, roll call 190Clerk of the House · July 3, 2025
- Final Senate vote, roll call 372U.S. Senate · July 1, 2025
- Why Susan Collins voted noSenator Susan Collins · July 1, 2025
- Fitzpatrick’s statement on the Senate amendmentRepresentative Brian Fitzpatrick · July 3, 2025
- Tillis votes against the billWFAE · July 1, 2025
- The Senate’s deciding voteAssociated Press · July 1, 2025
- Distributional effects of the enacted lawCongressional Budget Office · August 11, 2025
- Tax provisions in the 2025 reconciliation lawCongressional Research Service · R48611
- Deductions for working Americans and seniorsInternal Revenue Service
- Guidance on qualified tips and overtimeInternal Revenue Service
- Employer’s Tax Guide: payroll treatmentInternal Revenue Service · Publication 15
- Treasury’s first filing-season resultsU.S. Treasury · June 2, 2026
- Health provisions of Public Law 119-21Congressional Research Service · R48633
- Which states face the Medicaid changesKFF
- Federal framework for Medicaid work requirementsCenters for Medicare & Medicaid Services
- Nebraska’s Medicaid work requirementsNebraska Department of Health and Human Services
- Medicaid: what to watch in 2026KFF
- Hospital association’s reconciliation resourcesAmerican Hospital Association
- Nursing facilities and staffing policyKFF
- The federal Planned Parenthood ban expiresKFF
- Closures and reduced care after the funding banAssociated Press · July 6, 2026
- SNAP participation trackerCenter on Budget and Policy Priorities · October 23, 2026
- Agriculture and nutrition provisionsCongressional Research Service · R48775
- SNAP and the states’ new costsNational Conference of State Legislatures
- SNAP quality control and payment errorsU.S. Department of Agriculture
- Higher education provisionsCongressional Research Service · R48727
- Final student-loan repayment and borrowing ruleU.S. Department of Education
- Graduate PLUS loans and the July 2026 changesFederal Student Aid
- Temporary changes to professional-student loan limitsNational Association of Student Financial Aid Administrators
- Federal school-choice tax creditInternal Revenue Service
- Workforce Pell implementationFederal Student Aid
- The clean-energy credit deadlinesInternal Revenue Service
- The $5 trillion increase in the debt ceilingOffice of the Law Revision Counsel
- Energy and emissions impacts of the final lawRhodium Group
- Clean Investment Monitor: Q2 2026Rhodium Group / MIT
- Homeland Security appropriations in the lawCongressional Research Service · R48704
- Defense funding in the reconciliation lawCongressional Research Service · IN12580
- The law’s updated deficit and growth effectsCongressional Budget Office · February 11, 2026
- Housing provisionsCongressional Research Service · R48743
- Consumer Financial Protection Bureau funding changesCongressional Research Service · IN12578
- Commerce provisions: aviation, space and spectrumSenate Commerce Committee
- The new remittance-transfer taxInternal Revenue Service
- Gambling-loss deductions from 2026Internal Revenue Service · Publication 505